DOWNLOAD SAVILLS Q1/2025 MARKET BRIEF
Savills Market Brief Q1/2025 offers a comprehensive overview of the real estate market in Ha Noi and Ho Chi Minh City, covering residential, commercial, and hospitality sectors. This document assists investors, businesses, and individuals interested in the Vietnamese real estate market in making informed decisions.
Total Registered FDI Q1/2025
Q1/2025 witnessed a multitude of positive signals from the Vietnamese economy, with an impressive GDP growth of 6.9% – the highest level recorded since 2020. Buoyant import-export activities, a robust surge in FDI, a distinct recovery in tourism, and sustained momentum in domestic consumption were key highlights. However, alongside these promising indicators, emerging challenges are becoming apparent, such as a contraction in the trade surplus and a persistently high number of business withdrawals.
Download Savills Market Brief Q1/2025 for insights into Viet Nam’s property sector.
RESIDENTIAL REAL ESTATE OVERVIEW
Apartment
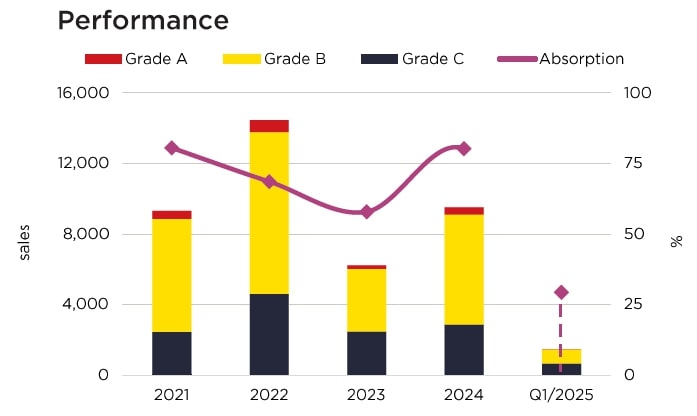
HCMC's apartment Market in Q1/2025 experienced a constrained influx of new supply, primarily attributable to the Tet holiday period, which coincided with transaction volumes decelerating due to a scarcity of affordable housing options. Nevertheless, a positive outlook prevails, underpinned by advancements in the legal framework and the urban planning initiatives for Thu Duc City.
Figure: HCMC Apartment Performance Q1/2025
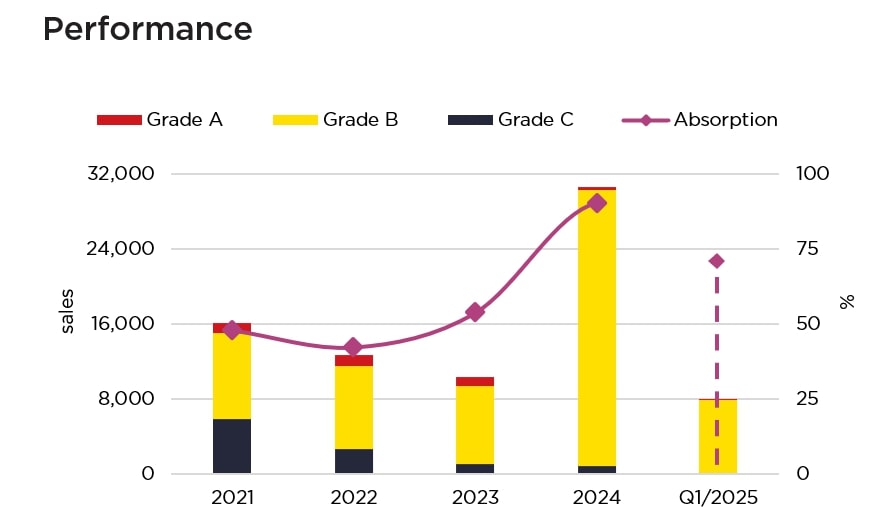
The Ha Noi apartment market in Q1/2025 witnessed robust activity, with 7,914 units sold and primary prices surging by 32% YoY. In contrast, the secondary market experienced a slight price decrease, marking the first decline in five years. Notably, the price gap between primary and secondary markets for Grade A projects reached its highest level.
Figure: Ha Noi Apartment Performance Q1/2025
New supply remains limited but is expected to improve with support from revised planning and legal frameworks focused on boosting development.
Troy Griffiths, Deputy Managing Director, Savills Viet Nam
COMMERCIAL REAL ESTATE OVERVIEW
Office
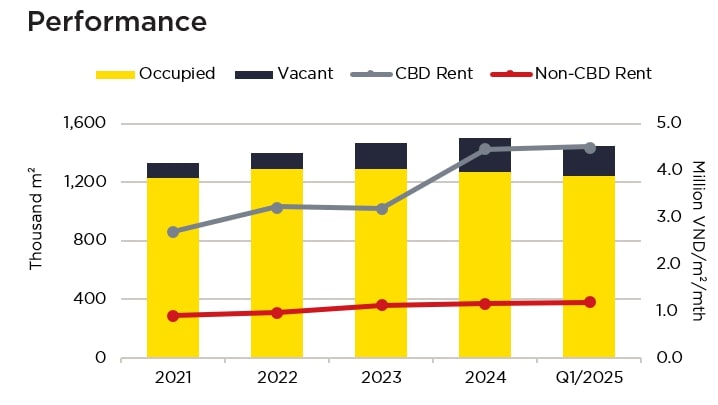
HCMC Office Market in Q1/2025 demonstrated relative stability, with a marginal increase in rental rates despite a slight contraction in occupancy levels. Grade C properties constituted most of the supply, while Grade A developments in non-central business districts exhibited superior occupancy rates. Tenant relocation and expansion initiatives remained the primary drivers of leasing activity, spearheaded by the ICT sector.
Figure: HCMC Office Performance Q1/2025
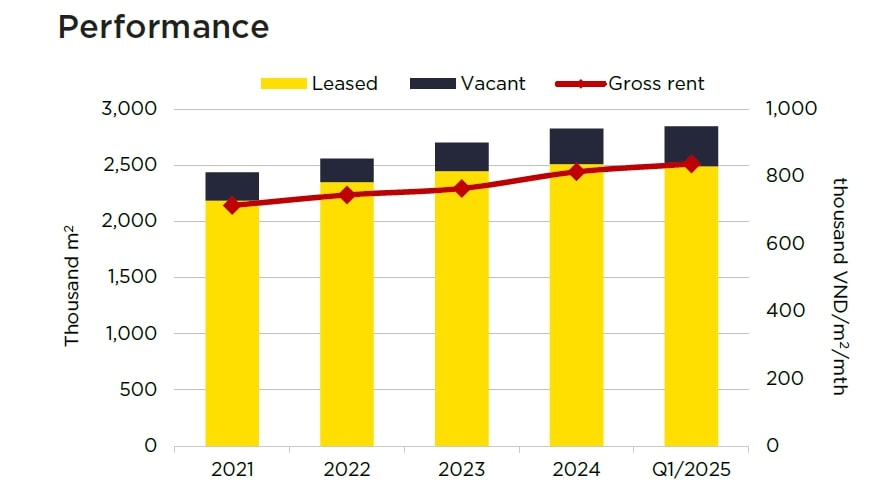
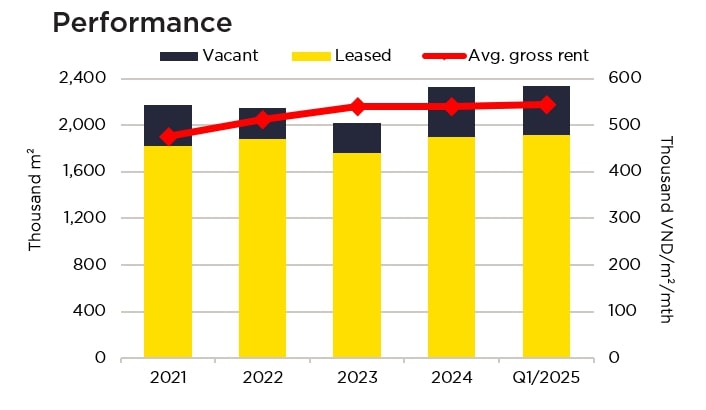
In Ha Noi's Q1/2025 market, total supply reached 2.33 million sq m, marking a 10% YoY increase, predominantly driven by the Grade B segment. Grade A supply remained scarce, particularly in the central areas. Significant transaction volumes were concentrated in high-value sectors such as consulting, ICT, and FIRE.
Figure: Ha Noi Office Performance Q1/2025
A tenant-favourable office market makes rent hikes risky for developers. The Land Law ensures long-term rights, offering stability for future planning.
Hoang Nguyet Minh, Senior Director, Commercial Leasing, Savills Ha Noi
Retail
HCMC's Retail Market in Q1/2025 maintained a robust occupancy rate of 94%, buoyed by consistent demand from the F&B, entertainment, and furniture sectors. Overall rental rates remained stable, with a slight upward trend when excluding the impact of new developments. Despite land scarcity, future supply is primarily concentrated in the central areas. The outlook is positive, supported by a 14% increase in total retail sales and a target of 18% for 2025.
Figure: HCMC Retail Performance Q1/2025
The Ha Noi retail market demonstrated positive momentum in Q1/2025, with average rental rates increasing by 6% YoY and achieving an occupancy rate of 86%. Notably, tenant demand is undergoing a distinct shift from Food & Beverage (F&B) establishments towards convenience stores, fashion retailers, and cosmetics outlets. The newly enacted 2024 Fire Prevention and Fighting Law is also incentivizing retailers to transition from leasing space in shophouses to securing premises within shopping centers that offer more robust fire safety systems.
Figure: Ha Noi Retail Performance Q1/2025
A continued shortage of supply combined with the expansion of international retailers has tightened market prospects, especially in CBD.
Cao Thi Thanh Huong, Senior Research Manager, Savills HCMC
HOSPITALITY REAL ESTATE OVERVIEW
Hotel
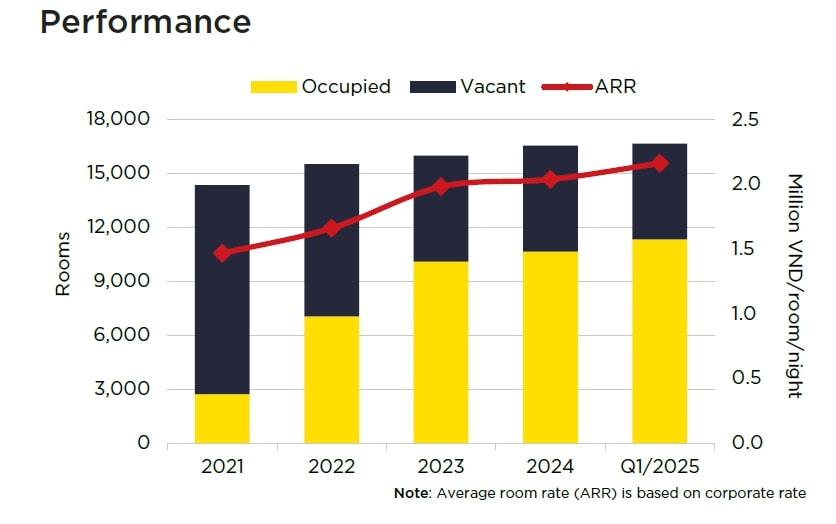
HCMC's hotel market sustained its recovery in Q1/2025, with supply reaching 16,666 rooms and occupancy at 68%. Room rates remained stable, supported by a consistent business and short-stay demand. The outlook is positive, driven by targets for increased international and domestic tourist arrivals, aligning with the impetus from new infrastructure, including international Terminal 3, paired with tourism promotion initiatives.
Figure: HCMC Hotel Performance Q1/2025
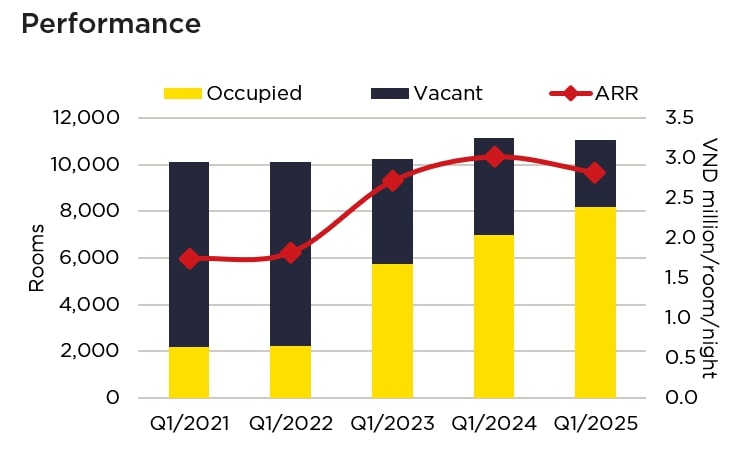
Ha Noi's hospitality market experienced positive momentum in Q1/2025, with occupancy reaching 76%, a notable 11% YoY increase driven by a surge in international arrivals, particularly from China. The average room rate slightly increased compared to the same period in the previous years. Looking ahead, the market is set to welcome nearly 12,000 new rooms, with supply focused on the western districts and surrounding areas, driven by the anticipated entry of several major international hotel brands.
Figure: Ha Noi Hotel Performance Q1/2025
The outlook is positive amid ambitious tourism targets, limited pipeline and ongoing infrastructure improvement.
Neil MacGregor, Managing Director, Savills Viet Nam